BC Home Buying Costs: A Cash Plan From Deposit to Move-In

Your BC home-buying budget needs to answer two different questions: how much of your own money the purchase will use, and how much must be available on each payment date. The deposit belongs inside your down payment, not on top of it. Taxes, professional bills and closing adjustments are separate. Moving expenses reduce what remains, while a refundable move-in deposit temporarily ties up cash without necessarily becoming a permanent expense.
The useful number is therefore not just “cash needed to close.” It is the liquid balance left after closing and moving, compared with the reserve your household needs. Build that balance from actual funds, documented financing and property-specific costs. A percentage allowance can start a conversation, but it cannot finish this calculation.
Put the deposit on the calendar, not on the bill twice
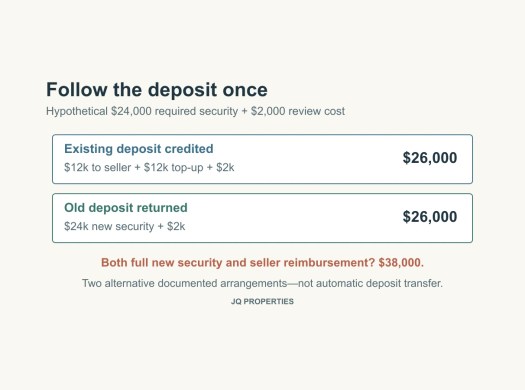
Suppose a hypothetical buyer plans to put $180,000 toward a $900,000 home and borrow $720,000. A $45,000 deposit paid under the purchase contract leaves $135,000 of the down payment still to provide. It does not increase the buyer’s purchase-price contribution to $225,000. BCFSA confirms that, when a transaction completes, the deposit forms part of the total down payment agreed with the lender. The amount and payment timing come from the transaction, so do not substitute an assumed standard percentage for the signed terms. BCFSA’s deposit guide.
There is another easy double count: subtracting the deposit from a bank balance that already reflects its payment. Date your opening balance. If it is the balance before the deposit, show that payment below it. If it is today’s balance after the deposit cleared, show only the remaining down payment among future withdrawals.
A deposit is also not an emergency account you can access while the purchase is pending. Record its holder and receipt. If a transaction collapses, entitlement to the money and its release are separate questions; do not assume an immediate refund can fund another offer. Ask the professionals handling the contract about the actual circumstances.
Work from the mortgage funds that will actually arrive
The purchase-price gap is the price less the financing available for that price. Your lender should confirm the loan structure, any mortgage-insurance treatment, charges deducted from the advance and conditions remaining before funding. Record separately whether a fee is paid from savings or financed; counting it in both places overstates cash needed, while assuming it is financed without confirmation understates it.
Preapproval is not final approval for every property. The lender can still assess the home and the borrower’s current circumstances. A lower advance creates a larger buyer-funded gap even when the purchase price has not changed. FCAC’s mortgage preapproval guidance.
Ask for the date the closing professional needs cleared funds, not just the contract’s completion date. Confirm bank-draft or transfer instructions through a trusted contact method. An investment sale, family gift or sale of another home belongs in the available-cash figure only when its timing and acceptability are established. Keep uncertain receipts beside the budget as possible funding, not inside the opening balance.
For buyers also selling a home, write a second cash schedule for the sale: outstanding mortgage, discharge costs, agreed selling expenses and the expected net proceeds. A purchase deposit due before those proceeds arrive is a timing problem even if the combined transactions leave plenty of equity. Any bridging arrangement needs its own approval and cost.
Keep purchase taxes separate from the down payment
For an ordinary full-interest transfer with no relief, BC’s general property transfer tax is 1% on the first $200,000 of fair market value, 2% on the next $1.8 million and 3% above $2 million. A further 2% applies to residential value above $3 million. On the hypothetical $900,000 fully residential transfer, the general tax is $2,000 plus $14,000: $16,000. This illustration assumes that $900,000 is the correct tax value and no exemption applies. Mortgage debt is not a deduction from that tax value. Property Transfer Tax Act, sections 1, 3 and 3.01.
First-time buyer and newly built home relief require their own checks. Do not simply mark the purchase “first home” and erase the tax. Ask the filing professional to identify the specific program, purchaser eligibility, property limits and continuing occupancy obligations. Keep an unconfirmed reduction outside the amount reserved for closing.
Additional property transfer tax is another line, not a replacement for the general tax. Where it applies, BC’s current rate is 20% on the relevant foreign entity’s or taxable trustee’s proportionate residential interest in specified areas. The simple example below assumes no additional tax is payable. If that assumption is unresolved, it is not a usable budget for your transaction. Federal permission to buy is a separate legal question. Start with the international-buyer eligibility guide before treating a larger tax reserve as permission to proceed. BC additional-tax rules.
New or substantially renovated housing can raise a separate GST question. Read the actual price clause: is tax included, payable in addition, or shown net of a rebate? CRA distinguishes between a builder paying or crediting an eligible first-time buyer’s rebate and the buyer applying directly when the builder does not. A later application is not a closing credit. Have the contract treatment and eligibility confirmed before entering a rebate as money available on completion. CRA’s builder-purchase rebate instructions.
Replace broad fee allowances with scoped quotes
A legal or notarial quote should say whether it includes taxes, title searches, registration, lender work, title insurance where used and other disbursements. Compare the complete scope rather than the headline professional fee. Ask about extra work specific to your file, such as multiple lenders or signing arrangements.
Public registration charges are useful checks, but they are not the whole closing bill. LTSA’s customer fee listing effective April 1, 2026 shows $83.82 for an indefeasible title and charge filing. A hypothetical file containing one of each would have $167.64 for those two filings alone; other searches, filings, services or professional charges may also be needed. Do not add that amount again if your quote already includes it. LTSA’s current fee schedule.
Inspection, specialist investigation and appraisal costs need their own payment dates. Record whether the lender or buyer pays an appraisal, and what an inspection quote covers. A cost incurred while deciding whether to buy may remain spent even if you do not proceed. Set a search-stage allowance if you might investigate more than one home.
Insurance is equally property-specific. Give the insurer the actual address and relevant condition or occupancy facts. For a strata property, discuss the relationship between the corporation’s insurance and the owner’s coverage. Include any premium payable before completion, but do not count an annual premium upfront and then repeat the same months in the move-in allowance.
Read adjustments as a settlement, not another annual bill
The statement of adjustments reconciles amounts between the parties. It can include a buyer reimbursement for costs the seller has prepaid or a buyer credit for an amount allocated to the seller. Ask what period each adjustment covers and what document supports it. BCFSA identifies preparation of this statement, the transfer documents and the property transfer tax return among the closing professional’s functions. BCFSA’s completion guide.
For planning, enter net adjustments with a sign: a debit increases cash needed; a credit reduces it. Do not add the full annual property-tax bill to a tax adjustment without understanding who will actually pay that bill. Keep your ongoing ownership budget separate so that the next tax payment is funded when due.
On a condo purchase, ask about strata fees, a special levy and any agreed allocation. On a tenanted property, ask how rent and tenant deposits are handled in the closing records; money you must hold or account for is not spare spending money. The contract and closing review determine the transaction’s treatment, not a generic checklist.
A complete cash example you can reconcile
The following is a hypothetical resale purchase, not a quote or recommended reserve. It assumes $245,000 of cleared buyer cash before any listed payment, a $900,000 price, a $720,000 mortgage available toward that price, no GST on this transaction and no PTT relief or additional PTT. All service and moving figures are invented planning inputs, inclusive of any applicable taxes for this example.
| Cash movement | Amount | Cash left |
|---|---|---|
| Opening cleared cash | $245,000 | $245,000 |
| Inspection and investigation, paid before completion | −$900 | $244,100 |
| Contract deposit, part of $180,000 down payment | −$45,000 | $199,100 |
| Remaining down payment | −$135,000 | $64,100 |
| General property transfer tax | −$16,000 | $48,100 |
| Legal and closing package, including quoted disbursements | −$2,400 | $45,700 |
| Net adjustment debit | −$1,200 | $44,500 |
| Moving and immediate setup expenses | −$3,400 | $41,100 |
| Refundable move-in deposit, not yet returned | −$500 | $40,600 |
The anticipated closing funds are $135,000 + $16,000 + $2,400 + $1,200 = $154,600. The $900 inspection is already paid and is not part of that future request. Moving expenses and the refundable deposit require another $3,900 outside the closing funds.
After those payments, $40,600 remains liquid. If this household chooses to protect $30,000, its unallocated cushion is $10,600. The $500 held as a refundable deposit is not included in that cushion. If it is returned in full, liquid cash becomes $41,100; a refund is not guaranteed by this example.
You can cross-check the opening $245,000 another way: $180,000 toward the price, $23,900 in other payments, $500 temporarily held, and $40,600 still liquid. Those figures reconcile exactly. This makes a missing or duplicated payment easier to spot than a single “closing costs” estimate.
Test the number that could make the plan fail
Use the same ledger with one changed fact. If net mortgage funds fall by $12,000, the buyer must supply $12,000 more. Closing funds rise to $166,600, the post-move liquid balance falls to $28,600, and the chosen $30,000 reserve is short by $1,400. That is a financing decision to resolve before relying on the budget; it is not fixed by relabelling the reserve.
Alternatively, keep the mortgage unchanged and add $3,500 of overlapping accommodation and storage. The liquid balance becomes $37,100 and the cushion above the reserve becomes $7,100. Different households need different reserves: an older detached home, uncertain employment income and an upcoming strata levy are not the same situation as a stable-income household with recently replaced major systems.
To adapt the ledger, write the opening-balance date, replace every amount, and mark each future payment with its payee and deadline. Use the signed contract for the deposit, the lender for the advance, the filing professional for taxes and adjustments, and the actual provider for service costs. If two figures disagree, resolve their scope and date rather than averaging them.
The final check is simple: can you explain every difference between this ledger and the closing statement, and will enough usable cash remain after the move? For help identifying property-specific questions before making an offer, request a planning conversation. Tax, financing and legal conclusions belong with the professionals responsible for those parts of the purchase.
By Justin Qiao, Personal Real Estate Corporation, Justin Qiao Group | RE/MAX Crest Realty.
General information checked September 8, 2026. Transaction-specific facts and subsequent rule changes can change the result.