GST on New Homes in BC: Current Rebates and Closing Cash
By Justin Qiao, Personal Real Estate Corporation, Justin Qiao Group | RE/MAX Crest Realty.
A GST rebate can reduce the cost of an eligible new home without reducing the money you must deliver on completion day. The difference is whether the builder actually pays or credits the rebate under your agreement, or you pay the tax and apply to CRA afterwards. Start with the taxable price and the contract's rebate treatment, not an advertised “GST-free” description.
The first-time home buyers' GST/HST rebate is now an operating program, with applications open. It is no longer merely a proposal. This guide uses rules checked on September 8, 2026 and focuses its calculations on buying a new BC home and its land from the same builder. Owner-built homes, leased-land purchases, co-op shares and rental property require their own application and calculation routes. CRA rebate status
Establish the tax before subtracting a rebate
Sales of new or substantially renovated housing are generally taxable; most sales of previously occupied residential housing are exempt. A renovated listing is not automatically a substantially renovated home for GST purposes. The property's actual history and transaction matter. CRA home-construction tax guidance
The GST rate in BC is 5%. On an assumed $900,000 price before GST, the tax is $45,000 and the price plus tax is $945,000. If a contract simply states a $945,000 GST-inclusive price with no rebate adjustment, dividing by 1.05 recovers the $900,000 before-tax amount. But do not use that shortcut when the stated amount is already net of a rebate, includes other supplies, or involves an assignment. Obtain the builder's actual price-and-tax breakdown. CRA GST/HST rates
Keep the contract price, tax, rebate credit, deposit and mortgage advance on different lines. “Included in the price” says how a number is presented; it does not by itself establish that you qualify for a rebate.
Two federal rebates, not two refunds of the same tax
The ordinary GST/HST new housing rebate is not restricted to first-time buyers. For the straightforward BC house-and-land builder purchase discussed here, its federal amount is generally 36% of GST, up to $6,300, with a reduction above a $350,000 before-tax purchase price and no federal rebate at $450,000 or more. Other eligibility conditions still apply. Do not substitute a property's current BC Assessment value for the required purchase-price measure. CRA new housing rebate guide
The newer first-time buyer rebate can bring combined federal relief to all the GST on an eligible home priced at $1 million or less, up to $50,000. Relief phases down between $1 million and $1.5 million; it is unavailable at $1.5 million or more. Where the ordinary rebate also applies, the first-time amount is a top-up, not a second repayment of the same GST. CRA first-time rebate explanation
For example, assume a qualifying sole buyer pays $320,000 before GST. Tax is $16,000. The ordinary rebate is $16,000 × 36% = $5,760. If the buyer also satisfies the first-time program, the remaining top-up is $10,240, bringing total relief to $16,000—not $21,760. If the builder already credited $5,760, only the additional eligible amount remains to be claimed.
The agreement date is different from the buyer's eligibility date
For an eligible house-and-land purchase from a builder, the purchase agreement must be entered into on or after March 20, 2025 and before 2031. Construction must begin before 2031 and be substantially completed before 2036; ownership must transfer before 2036. The buyer must acquire the home for their own primary residence and be its first individual occupant after substantial completion. The program's Royal Assent date was March 12, 2026, but that is not the agreement eligibility starting date. Enacted legislation, Part 2
For this purchase type, first-time status is tested when ownership transfers. Generally, the claimant must be at least 18, be a Canadian citizen or permanent resident, and not have lived as their primary residence in a home they or their spouse or common-law partner owned during the relevant calendar year and preceding four calendar years. Neither the claimant nor their spouse or partner may previously have received this first-time rebate. This is not simply a “never bought in Canada” test. CRA eligibility criteria
For a transfer in 2026, review the ownership-and-occupancy history from 2022 through the relevant time in 2026, including foreign homes. Record who owned each home and who actually lived there. Do not infer eligibility merely because the new contract was signed while renting.
A multi-buyer purchase is not automatically excluded because one individual has owned before: at least one qualifying first-time purchaser must meet the relevant conditions and claim the rebate. But a corporation or partnership on ownership changes the analysis; the individual new-housing rebate route does not cover it. CRA multiple-buyer rules
Assignment or amendment of an agreement signed before March 20, 2025 does not reset that original date for this relief. The legislation also addresses cancellation and replacement primarily arranged to obtain the rebate. Preserve the original agreement and all later documents; do not rely only on the date on the latest signature page. Enacted anti-avoidance provisions
Compare the same purchase with and without a closing credit
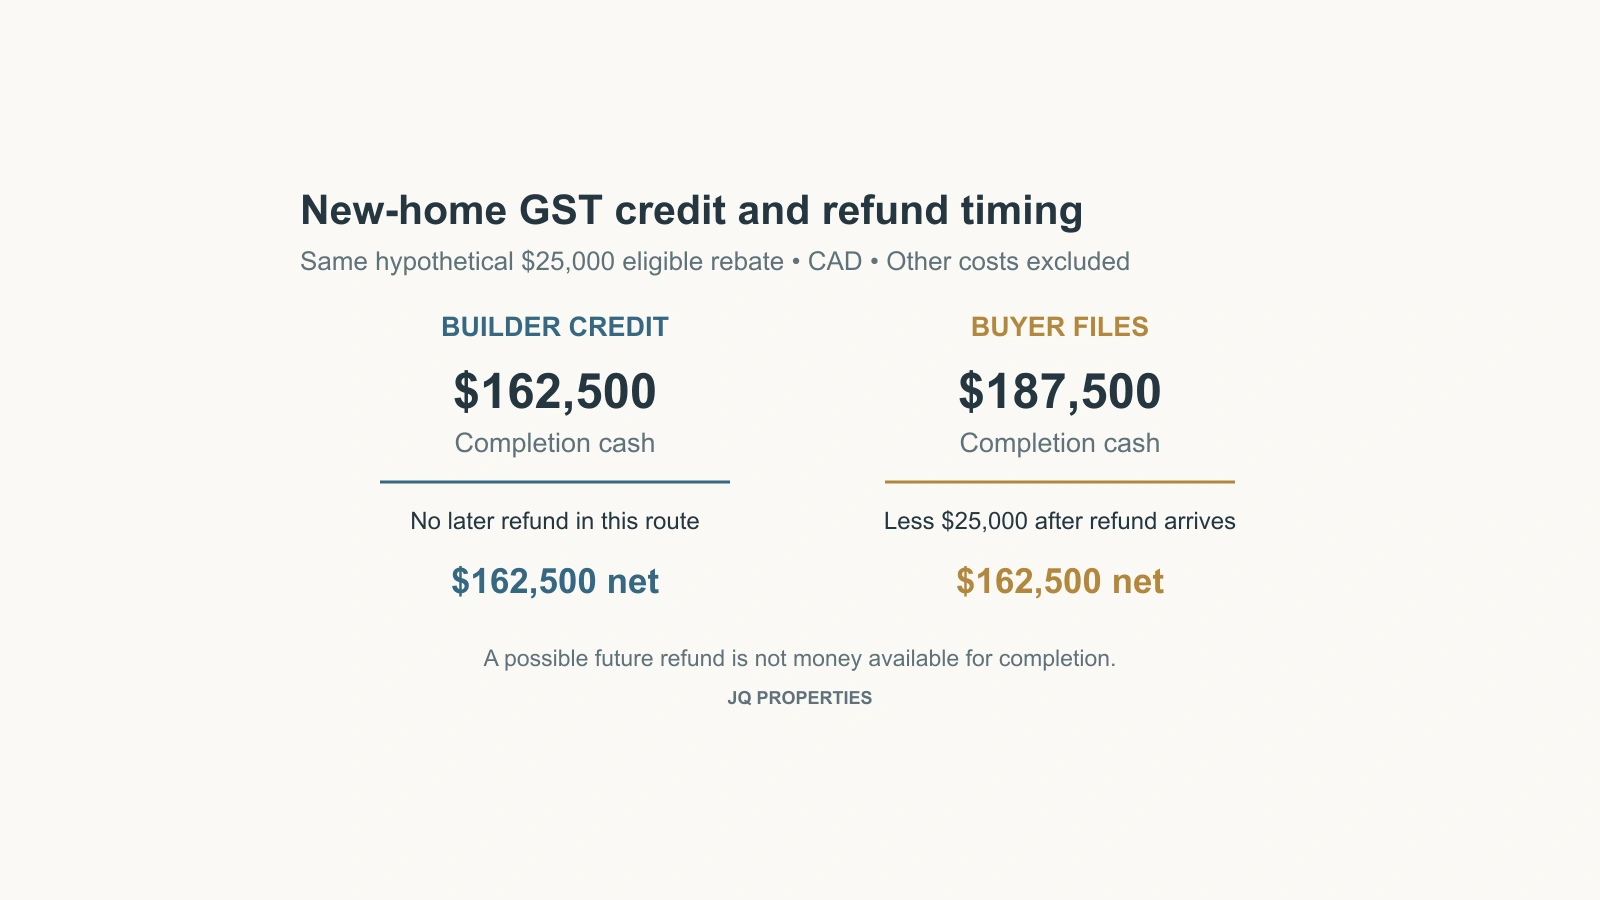
Consider a hypothetical eligible purchase at $1,250,000 before GST, with ownership and possession both transferring on the assumed completion date. Tax is $62,500. The first-time rebate is $50,000 × ($1,500,000 − $1,250,000) ÷ $500,000 = $25,000. It is not half of the $62,500 GST bill. CRA reduced-rebate example
Assume a $125,000 deposit has already been paid and the lender confirms a $1,000,000 net advance available for this purchase. Ignoring all other closing costs solely to isolate the GST effect:
| Agreed treatment | Remaining purchase funds at completion |
|---|---|
| Builder credits the full $25,000 eligible rebate | $1,250,000 + $62,500 − $25,000 − $125,000 − $1,000,000 = $162,500 |
| Buyer pays GST and later applies directly | $1,250,000 + $62,500 − $125,000 − $1,000,000 = $187,500 |
The second route needs $25,000 more at completion even if the eventual rebate is identical. There is no assumed processing date or guarantee of payment in this example. If the contract credit depends on eligibility and the buyer does not qualify, the $162,500 budget cannot stand without revisiting the contract and financing.
Use the GST rebate route and closing-cash record to connect the application route with the amount actually credited. It is a worked record, not a determination that a particular purchaser qualifies.
Choose the filing route before the paperwork is signed
When the builder agrees to pay or credit the rebate on a house-and-land purchase, the builder submits the application, normally using GST190 under type 1A. If no builder payment or credit is given, the buyer files under type 2, generally within two years after ownership transfers, online through CRA or by the current form's mail instructions. Do not file a duplicate claim for an amount already credited. CRA builder-purchase application instructions
There is a distinct route where the builder credited only the ordinary new housing rebate, including eligible purchases completed before Royal Assent: the buyer can apply for the additional first-time amount within the applicable deadline. Retain the earlier application and credit details so the prior relief is deducted correctly. Do not assume “already filed once” means no top-up is possible—or that it permits claiming the full tax twice. CRA additional-claim instructions
For an owner-built home, use the owner-built route, including GST191 and its construction worksheet where applicable. Its filing clock runs from a defined base date, not automatically the day you bought land or moved in. CRA owner-built application instructions
Leased land, co-op shares, mobile or floating homes and taxable assignments require the appropriate valuation and form treatment; do not feed them into the simple purchase-price examples above. Rental use instead calls for the separate rental-rebate rules. CRA rental property rebate guide
Finish with a dated tax-and-cash reconciliation
Before relying on the rebate, reconcile the original agreement, buyer history, intended occupancy, construction dates, ownership and possession dates, and the builder's credit. Ask who is filing and retain the signed application and submission record. Where possession and ownership differ, establish the actual GST payable date; special timing rules can apply to new condominium units. CRA tax timing rules
BC property transfer tax remains a separate calculation. The property transfer tax guide covers that cost; qualifying for one tax program does not settle the other. Our first-time buyer program guide helps place savings accounts and later tax credits in the wider plan.
Justin Qiao Group can help organize the purchase documents and closing questions for a new-home comparison. The useful result is not an optimistic rebate number: it is a supported application route and enough confirmed money for the day the purchase funds are due.