Using the Home Buyers’ Plan: Match the Withdrawal to Your Purchase Timeline
By Justin Qiao, Personal Real Estate Corporation, Justin Qiao Group | RE/MAX Crest Realty.
The Home Buyers' Plan can turn eligible RRSP savings into purchase funds, but the account balance alone does not tell you when that money can support your offer. Match the HBP withdrawal rules to the deposit deadline, your conveyancer's funding deadline and the date you acquire the home. A withdrawal can satisfy one program deadline and still arrive too late to pay a contractual obligation.
Work backwards from the cash you must deliver, while checking eligibility before making the withdrawal. Do not treat an RRSP withdrawal request, the actual withdrawal and money available in your bank account as the same event.
Confirm participation before scheduling the money
CRA currently permits up to $60,000 per eligible participant under the HBP. Joint buyers do not automatically qualify together: each person's participation depends on their own circumstances. HBP money and a qualifying FHSA withdrawal can support the same home, provided the applicable conditions are met for each withdrawal. CRA: Home Buyers' Plan overview
For the ordinary first-time-buyer route, CRA's test considers living in a home owned by you or your current spouse or common-law partner during the current year before withdrawal, excluding the immediately preceding 30 days, and the preceding four calendar years. You also need a written purchase or construction agreement, the required Canadian residency and an intention to occupy the qualifying home as your principal residence within one year. A mortgage pre-approval is not that purchase agreement. CRA: Participation conditions
Use the current T1036 questionnaire, including its separate questions for previous participation, disability-related situations and relationship breakdown. Those routes should not be guessed from a general timeline. The form also distinguishes a previous HBP balance from a January continuation of withdrawals begun the prior year. CRA: Current T1036 form
This is a different exercise from determining eligibility for BC property-transfer-tax relief or another first-time-buyer benefit. The first-time buyer program overview explains that broader landscape; the dates below concern the HBP.
Put two withdrawal limits on the calendar
Multiple HBP withdrawals normally belong in the calendar year of the first withdrawal or January of the following year. A new January does not create another $60,000 allowance for the same participation. Complete a separate T1036 for each withdrawal and provide it to the RRSP issuer. CRA: Making withdrawals
There is also an acquisition-related limit. For an ordinary eligible withdrawal, neither you nor your spouse or common-law partner may have acquired the qualifying home more than 30 days earlier. The January window does not override that condition. Special relationship-breakdown provisions require their own analysis. Income Tax Act, section 146.01
For example, suppose eligible buyers acquire a resale house on December 21, 2026, and the participant's first HBP withdrawal was December 10. January 20, 2027 is 30 days after acquisition. January 21 is 31 days after. Under the ordinary rule, a January 21 withdrawal is too late on that test even though it falls in January. January 31 is not a universal final withdrawal date.
These are calendar-day comparisons, not a promise that an institution processes withdrawals on any chosen date. Confirm the relevant acquisition facts rather than casually substituting the moving day. A purchase with unusual possession arrangements needs particular care.
The institution's processing schedule is a separate constraint
On the current T1036, the participant supplies a requested withdrawal date; the issuer records the date paid. Writing the date you need does not make processing instantaneous. Ask the institution what it needs, how it will handle the investments held in the account and when the funds will be available through the intended delivery method. CRA: T1036, Parts C and Area 2
Discuss a plan for the deposit before signing an offer with a short payment deadline. If the deposit depends on an HBP withdrawal that cannot be requested or completed in time, a later closing date does not solve the earlier obligation. Another verified source of available cash may be needed, or the proposed transaction timing may not fit your finances.
Ask your conveyancer when they need your remaining funds, not only when the transaction completes. Give your mortgage professional the same dated cash plan so the financing file and the legal closing instructions are based on consistent information. Do not assume that a program's tax treatment changes the lender's documentation requirements.
A late eligible withdrawal cannot pay an earlier bill
Consider a hypothetical buyer with $25,000 already available outside the RRSP. Assume all HBP participation conditions are met, there are no relevant recent contributions, and the following amounts and processing dates have been confirmed for this invented example:
| Event | Assumed date | Cash effect |
|---|---|---|
| Pay the contractual deposit | December 2, 2026 | $20,000 paid; $5,000 remains |
| First HBP withdrawal | December 10 | $40,000 withdrawn |
| Withdrawal available in bank | December 11 | Available cash rises to $45,000 |
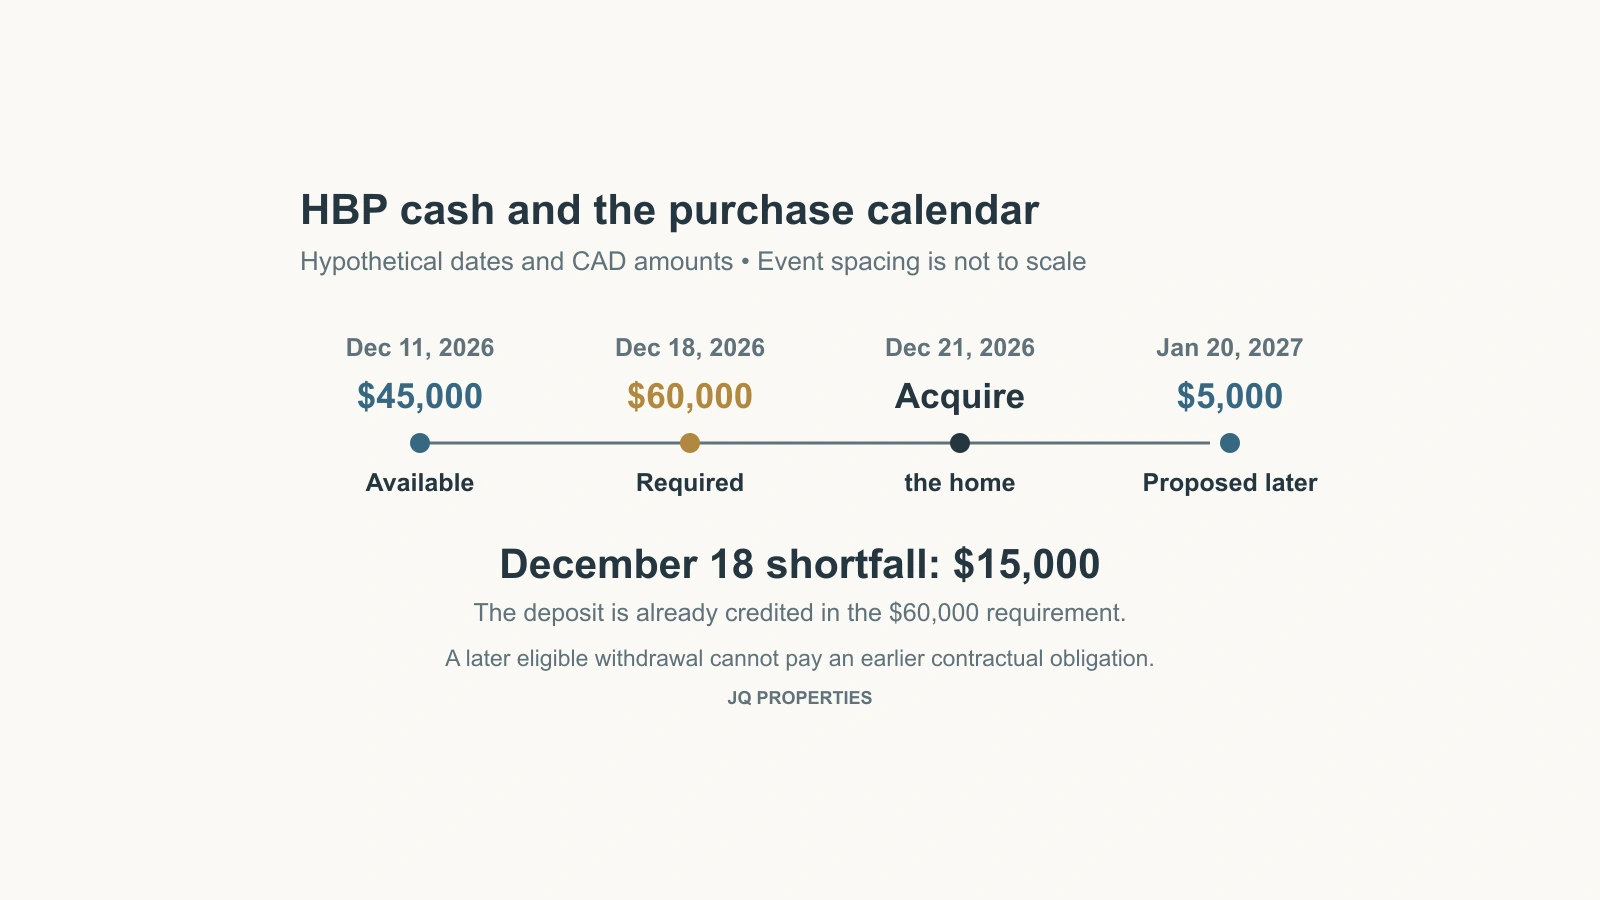
| Conveyancer needs remaining purchase funds | December 18 | $60,000 still required after crediting the deposit |
| Acquire the resale house | December 21 | Acquisition date for this example |
| Proposed additional HBP withdrawal | January 20, 2027 | $5,000, subject to all conditions at withdrawal |
At the December 18 funding deadline, the shortfall is $60,000 minus $45,000: $15,000. The planned January withdrawal does not reduce that December gap. Nor should the $20,000 deposit be deducted a second time; the quoted $60,000 requirement already allows for it.
The proposed HBP total is $45,000, below the current $60,000 ceiling. That does not make the purchase funded. The buyer must resolve the $15,000 gap before relying on this transaction plan. This example does not recommend borrowing the gap or assume such borrowing would be acceptable to the mortgage lender.
Use the HBP dates and cash worksheet to keep the program tests beside the actual payment obligations. It also shows the January 20/21 boundary so a date correction cannot be mistaken for a complete eligibility decision.
Recent RRSP contributions raise a deduction question
Do not simplify the HBP into “every dollar must sit untouched for 90 days.” CRA has a specific restriction on deducting certain contributions made during the 89 days before a withdrawal. Its calculation compares relevant contributions with the RRSP's value immediately after that withdrawal; some or all of those contributions may be non-deductible. Spousal RRSP contributions have related rules. CRA: RRSP deduction calculation
If you recently added money to obtain a tax deduction and then intend to withdraw it, collect contribution dates and account values before counting the expected tax benefit. That is a separate calculation from whether enough cash arrives at closing. The worksheet intentionally does not certify deductibility from an account opening date or a single contribution balance.
Keep the acquisition deadline and later repayments visible
The ordinary acquisition/building deadline is before October 1 of the year after the first withdrawal. A first withdrawal in 2026 therefore points to September 30, 2027 as the last day under that ordinary deadline, not October 1. CRA describes specific purchase/construction extensions; a delayed project is not automatically covered. CRA: Acquisition and extension conditions
If the purchase falls through, review the replacement-property and cancellation rules promptly. Cancellation is not simply depositing the money back without reporting it. CRA sets circumstances, repayment dates and documentation requirements; an unpaid amount can become income for the withdrawal year. CRA: Cancelling HBP participation
As checked September 8, 2026, the extended grace period covers first withdrawals made in 2026 through 2028: repayment starts in the fifth year following the first-withdrawal year. For 2026, that is 2031. This is reflected in CRA's current overview and the amended Act, not merely the original 2024 announcement. CRA: Current repayment relief, Income Tax Act, subsections 146.01(4.1)–(4.2)
For an ordinary $45,000 balance with no earlier repayments or income inclusions, $45,000 divided by 15 gives an initial annual repayment of $3,000. Designated HBP repayments are not deductible; a shortfall against the required annual amount is included in income. Follow your CRA HBP statement and correctly designate repayments rather than assuming any RRSP contribution does the job. CRA: Repayment mechanics
Justin Qiao Group can help align purchase deadlines with the questions for your financial institution and conveyancer. Confirm individual tax eligibility through the current CRA materials and appropriate advice; this general timeline is not a personal tax determination.

